Imagine you’re approached by a landlord who’s seen a three-bedroom property with clear potential to add value. It’s on the market for £200,000 and needs some refurbishment work to reach its full potential, but for a seasoned buy-to-let investor who’s experienced at buying properties, refurbishing them to add value and increasing rental income before moving on to the next project, it’s exactly the sort of opportunity they’re looking for.
The property’s priced to reflect its condition, needing a new kitchen, replacement bathroom, full redecoration and a rewire. In its current state, it could generate around £1,300 per month in rent. Following refurbishment, however, the property’s predicted to be worth £240,000 with rental income increasing to around £1,600 per month.
While the work involved might put some buyers off, your client sees an opportunity to accelerate equity growth. They know that once the work is complete, the property could be a far more attractive proposition to tenants.
How does refurbishment buy-to-let work?
Designed for experienced landlords looking to carry out non-structural or modernisation works, our refurbishment buy-to-let range is suitable for a wide variety of projects that can make a significant difference to a property’s value and attractiveness to tenants, without requiring major structural alterations.
By providing a single, long-term buy-to-let mortgage from day one, it can help simplify the journey from purchase to completed investment property. Rather than arranging separate funding solutions, borrowers can access a long-term mortgage from the outset, complete the agreed refurbishment works and then move forward with a property that has the potential to deliver greater value and rental income.
We’ll provide an initial advance of up to 75% of the pre-works purchase price, or valuation if the case is for remortgage purposes. We assess our affordability calculation using the anticipated post-works rental income rather than the rent achievable in its current condition.
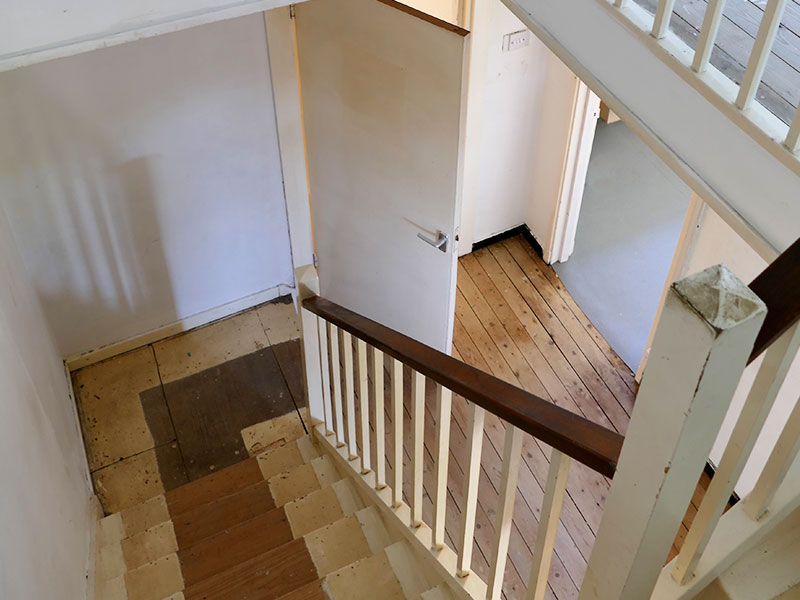
As the property is likely to be vacant while the refurbishment takes place, there’ll usually be no rental income being generated so we need the borrower to evidence they can cover the mortgage payments throughout the refurbishment period. We also need a full schedule of works, clearly setting out the improvements being made and the associated costs, alongside the projected post-works valuation. We’ll need evidence that shows the borrower can cover these costs, including a 10% contingency.
At initial completion, we hold back a retention, capped at 25% of the post-works valuation. The landlord can then get on with the refurbishment, which must be completed within 90 days of the initial mortgage advance being issued. Once all the agreed works have been completed, we’ll arrange a reinspection of the property to confirm its updated market value and rental income. Provided the works have been satisfactorily completed and the property achieves the expected valuation and rental assessment, we’ll release the retained funds.
More choice for brokers and landlords
In this example, you can see how a relatively modest refurbishment programme has helped transform a tired, vacant property into an attractive rental home. The landlord benefits from an increase in rental income of £300 per month, while also adding £40,000 in capital value.
Of course, every property project is different, but for landlords undertaking non-structural projects, our refurbishment buy-to-let range offers another option to consider. By providing a straightforward route to funding both the purchase and improvement of a property, it helps investors unlock additional value, improve rental prospects and bring underused properties back into productive use, all while benefiting from the certainty of a long-term buy-to-let solution.
To find out more about our range, take a look at our refurbishment product page. And don’t forget, if you’ve got a question or would like to discuss your case and would prefer to speak with a member of our team, you can always contact your business development manager or call our Broker Support Team on 01252 365888.
 Landlord tax considerations to be explored at CHL Mortgages’ latest webinar